Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
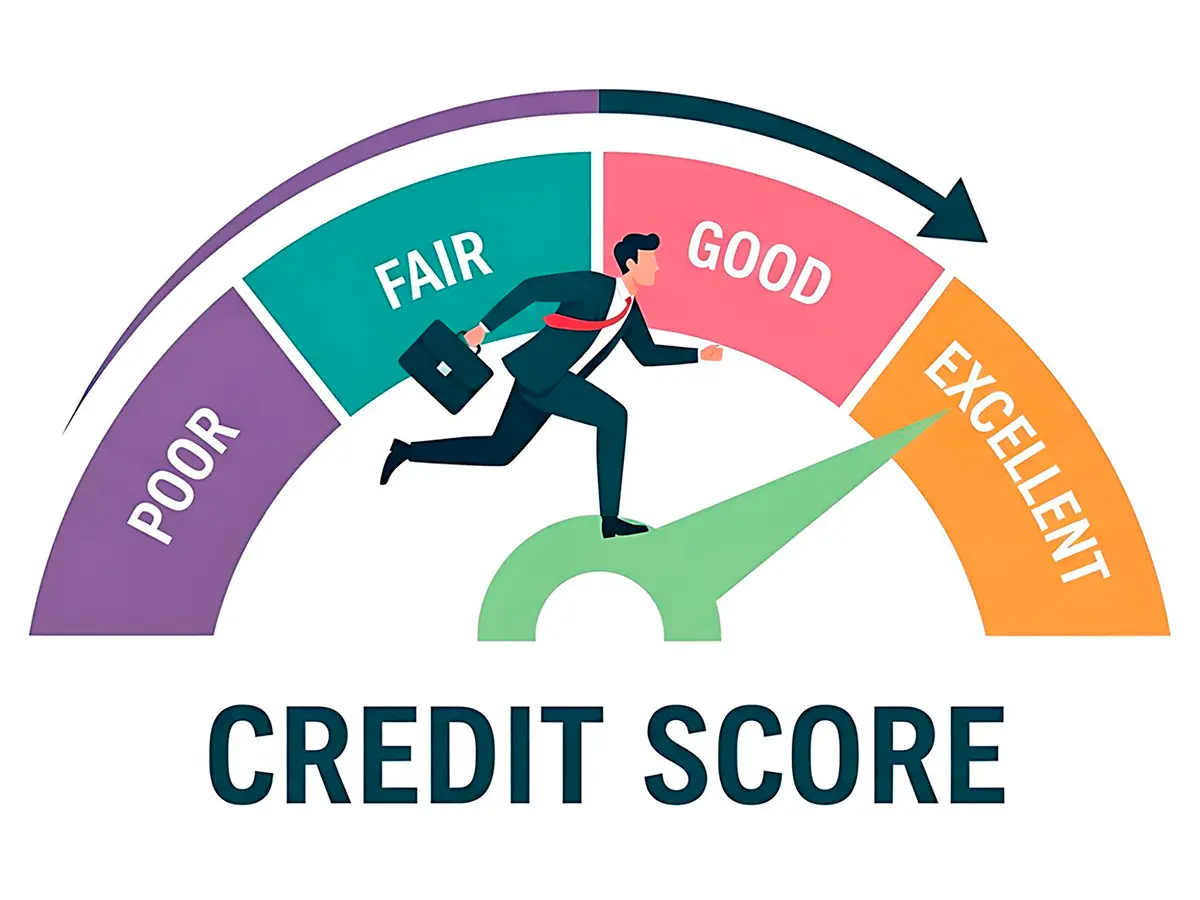
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
how does credit boost work: a practical, confidence-first look
I've heard the promises too: quick points, easy approval, instant wins. I'm skeptical by nature, but I also like flexible tools that respect my choices. So, how does credit boost work in real life? Short answer: it can help, sometimes modestly, and it's most useful when you know exactly what it does - and what it doesn't.
What "credit boost" actually is
It's an opt-in service that adds on-time payments from things like utilities, phone, streaming, or rent to your credit file. You grant read-only access to a bank account, the tool finds eligible payments, and it posts them as additional positive data. Some services report only to one bureau, and only certain scoring models will count those new entries. That detail matters more than any headline number.
The mechanics, step by step
- Consent and connect: You link an account; the service scans transactions for recurring bills.
- Select and verify: You choose which bills to include. On-time history is what helps.
- Report as tradeline or data point: The bureau file updates; scoring models that recognize it may adjust upward.
- Timing: Updates aren't instant for every lender. Expect a lag of days to weeks.
- Control: You can remove the data later, which restores your file to baseline.
The lift shows up mainly on newer scoring versions and many alternative models. Some lenders still use older versions, so impact can be uneven. I'm confident in the direction, but exact results vary by lender and model - measured uncertainty, not guesswork.
Who benefits most
- Thin files: Few accounts? Extra on-time history can add depth and stability.
- Recent, consistent payments: A clean streak on utilities or rent is the raw material.
- Close to a threshold: If you're a handful of points from a better rate tier, a small bump can matter.
It's less helpful if you have serious negatives or already carry a thick, decades-long file; the needle moves, but not by much.
Limits, trade-offs, and privacy
- Model coverage: Not every score counts these entries.
- Bureau scope: Some boosts hit only one bureau; lenders may pull a different one.
- Magnitude: Typical bumps are modest - think single digits to low double digits.
- Data access: You're granting read-only bank visibility; review terms and revoke if uncomfortable.
- Continuity: Stop paying a reported bill and the benefit can fade.
A quiet real-world moment
I linked my utility and mobile bills one evening, watched the new entries appear, and saw an 11-point uptick within a week. Not fireworks, but enough to nudge me into a better auto pre-qualification range. A later hard inquiry shaved a few points; the net was still positive. Small, steady wins count.
Alternatives and complements
- Report rent through a reputable service.
- Use a secured card, keep utilization under 10 - 30%.
- Become an authorized user on a well-managed, low-utilization card.
- Dispute clear errors and set autopay to avoid late marks.
How to try it with confidence
- Before: Check which scores your target lender uses; screenshot current scores.
- During: Add only bills you consistently pay on time; confirm the update posted.
- After: Recheck in 7 - 30 days; if the lift doesn't help or you're uneasy about access, unlink.
Bottom line: a credit boost is a flexible, low-friction nudge - not a cure-all. Use it deliberately, keep your core habits strong, and you stay in control while your score trends upward.
Experian Boost is a free feature that can improve your FICO Score by adding household bill payments to your Experian credit report. Eligible ...
Yes, Experian Boost works. According to Experian, the average user sees a 13-point increase in their credit score. Experian Boost works best for ...
Does Experian Boost Strengthen Your Credit? - Using Boost lets your streaming, phone and utility payments "count" toward your Experian credit ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.